Most woodworking businesses need more than a homeowners policy. The main exposures are the shop building, its machinery, lumber and finished stock; injury or damage caused by shop operations; products that cause harm after they leave the premises; work done at customer locations; employees; and vehicles used for business. A business owner’s policy (BOP) is a common starting package that bundles property, liability and business-interruption coverage. It is not a complete answer by default, and it does not include workers’ compensation.
Does homeowners insurance cover a woodworking shop?
It may not, at least not fully. Extremely small businesses operated from home may need more property and liability coverage than a typical homeowners policy provides. That is a reason to check your policy, not proof that every home policy excludes every shop. Ask your insurer directly whether the machinery, stock, tools and any customer work you perform at home are covered under your current policy, and whether a business add-on or a separate commercial policy is needed.
The exposure map
The table below lists each exposure, the coverage to discuss with an insurer, and the gap most often worth checking. Coverage names vary between insurers, so use the table as a list of questions rather than a list of products.
| Exposure | Coverage to discuss | Gap to check |
|---|---|---|
| Building, machinery, lumber, stock and raw materials | Commercial property coverage, including how replacement value, equipment, inventory and debris removal are treated | A homeowners policy may not cover business property, and a BOP may not include every valuable item or every peril |
| Visitor injury or damage caused by shop operations | Commercial general liability, premises and operations terms | Exclusions and limits matter; general liability does not replace workers’ compensation or specialized liability cover |
| A product that injures someone or damages property after sale | Products-completed operations coverage and its limits | Making or selling a product creates exposure even if you only distribute it, and policy conditions apply |
| Custom installation or work at a customer site | Completed-operations liability and any customer or general-contractor insurance requirements | Coverage follows the work you actually perform and the wording of the policy |
| Tools taken off premises and work in progress | Whether mobile equipment and customer work in progress are insured, where, and at what value | Shop property cover does not automatically follow tools or unfinished work to every location |
| Employees and workplace injuries | Workers’ compensation, including state requirements and exemptions | Rules vary by state, and workers’ compensation is separate from a BOP |
| Business vehicles and deliveries | Business auto coverage, and how personally owned vehicles used for business are treated | Personal auto cover may fall short when a vehicle is used mainly for business |
| Fire, electrical faults and business interruption | Property and business-income terms, plus documented fire controls | Recovery depends on the covered cause of loss, any waiting period, limits and exclusions |
What a BOP does and does not settle
A BOP typically combines property, liability and business-interruption coverage in one package, which makes it a sensible place to start for a small shop. Eligibility and limits vary by insurer, though, and a package sold for a retail office may not suit a shop with heavy machinery, flammable finishes or a product line. Treat a BOP quote as a draft to be checked line by line against the exposures above, not as the finished program.
#1 Best Overall
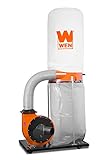
- Circulate up to 1,300 cubic feet of air per minute
- Attach up to two tools at a time with the dual 4-inch air inlets
- Vertical collection bag holds up to 50 gallons of dust
- 14-amp motor rotates the 10-inch steel impeller up to 3450 RPM
- Includes mobile base with four swivel casters for easy mobility
Liability from the shop and from products
Premises and operations
General liability addresses certain bodily-injury and property-damage claims that arise from your premises and day-to-day operations, subject to policy terms. A visitor who is hurt on the shop floor or a neighbor whose property is damaged by shop activity would typically be a question for this coverage. Ask which claims are excluded and what the per-occurrence and aggregate limits are.
Products after sale
A shop that manufactures or sells goods should understand products-completed operations exposure. If an item causes injury or damage after it has left the premises, the claim can arrive long after the sale. Triple-I’s Risk Management Basics describes product-liability risk management as keeping records over a product’s life and designing and testing products carefully. Keep design notes, inspection and test records, warnings and a complaint log that match what you sell.
Rank #2
- 5.7-amp brushed motor combined with the 6-inch impeller moves up to 660 cubic feet of air per minute
- 4-inch dust port allows for connection to your favorite woodworking tools
- Compact design includes an onboard carrying handle for easy storage and transportation
- Measures in at 34.25 x 13 x 14.2 inches in size with a weight of 17 pounds
- Features lockable swivel casters, an optional wall mount, a 12-gallon 5-micron zippered collection bag, and a two-year warranty
Work at customer locations
Artisan-contractor guidance identifies tools and equipment moved between sites, the value of work in progress, customer liability and business vehicle use as issues to review. Before you accept a job, ask your insurer:
- Are tools kept in a truck or trailer covered, and at what value?
- Is work in progress at a customer’s site covered, and is customer-supplied material included?
- Does liability continue after you hand over completed work, and for how long?
- Are subcontractors required to carry their own coverage, and do you need certificates of insurance from them?
- Do the customer’s contract or a general contractor require specific limits or endorsements you do not currently hold?
Employees and workers’ compensation
Workers’ compensation is not part of a BOP. Depending on state law and the circumstances of each worker, it may be mandatory, and state thresholds and exemptions differ. Confirm the requirements with your state’s workers’ compensation authority or a qualified insurance professional before you hire, and record which workers are employees and which are independent subcontractors.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #3
- Powerful 7.4-amp induction motor combined with the 9-inch impeller moves up to 600 cubic feet of air per minute
- 4-inch dust port allows for connection to your favorite woodworking tools
- Mount the unit to the wall of your shop for accessible dust collection whenever you need it
- Features an onboard carrying handle, swivel casters, a 15-gallon 5-micron zippered collection bag, and a two-year warranty
- Measures in at 43.3 x 17.7 x 20.1 inches in size with a weight of 41.1 pounds
Fire controls and written records
Insurers and risk guidance treat fire prevention as both a loss-control measure and evidence that you took reasonable precautions. Triple-I’s Risk Management Basics includes this fire-safety checklist question: “Are employees trained in fire safety? Do they know exactly what to do if a fire starts?” Practical controls that follow from it include:
- Training every employee in fire safety, and confirming they know the evacuation and response steps.
- Keeping extinguishers in place, serviced and in working order, and making sure staff know how to use them.
- Selecting extinguisher type and capacity for the hazards the shop actually has, and confirming local requirements with the local fire department or a qualified fire-protection supplier. The source does not recommend a brand or model.
- Checking electrical systems on a regular schedule and recording the results.
- Keeping purchase, maintenance and training records so you can show what was done.
How to compare policies
Headline premium is a poor basis for comparison. Line up quotes on these axes instead:
Rank #4

- 【HIGH EFFICIENCY】 Our DEWALT high efficiency dust separator can capture wood chips and other debris before they enter your vacuum cleaner, reducing suction loss due to clogged vacuum filters. Saves you the cost and time of expensive filter and dust bag replacement.
- 【WIDE APPLICATION】 This dust separator applies to most materials: wood chips, drywall dust, concrete dust, clay silica dust, soda water, cooling ash and soot, water, metal shavings, baking powder, grass and leaves, pets hair, drug waste and more.
- 【COMPATIBLE DESIGN】 The four-caster base of the dust collection system makes it very stable and easy to move around the workshop. Our 6 gallon shop vacuum system barrels are easy to empty. With 1-7/8" or 2-1/2" port, it can be used with most vacuum cleaners, such as household vacuum cleaners, industrial vacuum cleaners, sweepers, etc.
- 【PREMIUM MATERIALS】 All included parts are made of durable, high-quality and heat resistant materials with anti-clogging design for optimum efficiency.
- 【WHAT YOU GET】1 x DEWALT dust separator, 1 x 6 gallon poly bucket (vacuum cleaner not included), 2 x Hose Holder, 1xLid, 2 x Lid Sealing Strip, 2 x Lid Latch, 2 x Handle, 1 x 1-7/8" Hose, 1 x Wheel Bracket, 4 x Caster bushing, 4 x Screws (3.9 * 16 F), 4 x Screws (4.8 * 16 F),1 x 3 years limited warranty.
- Property scope and valuation: buildings versus business personal property, including equipment, inventory and raw materials, and how values are set.
- Liability scope and limits: premises and operations, products-completed operations, exclusions, per-occurrence and aggregate limits, and whether defense costs erode the limits.
- Business interruption: whether lost income and extra expenses are included and what triggers them.
- Offsite work: mobile tools, work in progress, subcontracting and completed work.
- Workers and vehicles: state workers’ compensation rules and business-auto treatment.
Steps to take before you buy or renew
- Inventory machinery, tools, lumber, finished stock and any products you sell, with purchase values and dates.
- Write a short description of the work: what you build, how you sell it, where you work, who helps you, and what you do off-site.
- Send that description and the inventory to a commercial insurance broker or agent, and ask for written answers to the questions in the sections above.
- Compare the quotes on the axes listed above rather than on premium alone.
- Record your safety training, extinguisher service and electrical checks, and keep copies with the policy.
- Report incidents promptly. Claim-reporting duties are set by each policy, so read the conditions section of yours.
Limits of this guidance
This is general U.S.-oriented insurance education drawn from Triple-I’s Risk Management Basics and artisan-contractor guidance, not legal, underwriting or policy-specific advice. The guidance does not establish a single insurance package, premium or extinguisher model that fits every woodworking operation, and it does not confirm that any particular insurer will accept a woodworking risk. State law, coverage availability, policy forms, exclusions, limits and premiums change and vary. Confirm the specifics with your state insurance authority, your insurer or a qualified professional.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minute