In the United States, a standard homeowners policy usually covers damage caused by a sudden and accidental release of water from indoor plumbing or a household appliance. Coverage still depends on the policy wording, deductible, limits, exclusions, maintenance history and the facts of the loss. A pipe that bursts today is treated differently from a leak that has been slowly soaking a wall for months. Floodwater entering from outside and sewer or drain backup are separate coverage questions and often need separate insurance or an endorsement.
This guide explains how insurers commonly classify each source of water, which parts of a homeowners policy may respond, what evidence matters and what to do after a loss. It is general U.S. information, not a promise that any particular claim will be paid. Your declarations page, endorsements and state law control.
As an Amazon Associate I earn from qualifying purchases.
Does homeowners insurance cover water damage?
Usually, yes, when the water came from a covered, sudden event inside the home. The National Association of Insurance Commissioners (NAIC) says homeowners policies cover damage from a “sudden and accidental” discharge from a plumbing system. That commonly includes the resulting damage from a burst supply pipe, a failed appliance hose or an unexpected overflow, subject to the contract.
“Covered” does not mean every cost associated with water. A policy may pay to repair resulting damage to insured property while excluding the worn-out pipe, failed appliance or long-term maintenance problem that caused it. The deductible is subtracted from an otherwise covered payment, and policy limits can cap what is available.
#1 Best Overall
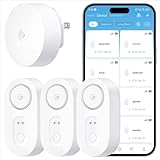
- Breakthrough 1804 ft Connectivity: Engineered with advanced Sub-1G long-range wireless tech, our leak detector maintains robust signals over unprecedented distances—reaching up to 1804 feet even through 5 dense walls. Secure every critical space in expansive properties, from deep basements to detached garages and distant outbuildings.
- Multiple Reminder Methods: Our water leak sensor supports multiple remote alarm. It can instantly send SMS, APP, and Email notifications to your phone (no matter how many times the SMS is used, it's free). Also, the water leak sensor flashes red and sounds a 105 dB alarm. Perfect for the basement, kitchen, or vacation home!
- Feature-Rich App: Receive instant push notifications. Use the “Find Device” feature to quickly trigger audible beeps to retrieve misplaced sensors. Add multiple email addresses through the APP, and your family and friends can also receive reminders when there is a water leak at home.
- Industry Leading IP67 Waterproof: Its IP67 waterproof rating ensures durability against spills, humidity, and accidental submersion.It can be used multiple times after wiping dry.
- Four-level volume adjustment: Customize your own alarm to fit your life! Use the app to adjust the volume in 4 levels, with a maximum alarm volume of 105 decibels. Whether it's day or night, whether it's in the bedroom or the basement, you can find the right volume.
Start by identifying the source, the timing and the path the water took. Then check the declarations page and endorsements for the applicable coverage section, deductible, limit and exclusions.
| Water situation | Usual treatment | Questions to verify |
|---|---|---|
| Burst pipe or sudden appliance-hose failure | Resulting damage is generally covered when the release was sudden and accidental. | Is the event covered under the plumbing or appliance provision? Does an exclusion apply? What deductible and limits apply? Is the failed component itself excluded? |
| Frozen pipe | Often covered if reasonable precautions were taken to maintain heat and prevent freezing. | Did the policy require minimum heat, water shutoff or other steps while the home was vacant? |
| Slow leak or seepage | May be excluded, especially when it developed over time or was not addressed promptly. | When did it begin, when was it discovered and what maintenance records show reasonable care? |
| Rain entering through a roof | Damage from a roof leak is typically covered under NAIC consumer guidance, but the cause and policy conditions matter. | Did a covered event create the opening, or did wear, deterioration or neglected maintenance cause it? |
| Runoff, snowmelt or groundwater entering from outside | Generally falls under the flood exclusion in an ordinary homeowners policy. | Is there a separate National Flood Insurance Program (NFIP) or private flood policy, and what does it cover? |
| Sewer or drain backup | Often requires specific water-backup coverage or an endorsement. | Does the declarations page list the endorsement, its limit, deductible and definition of backup? |
Does homeowners insurance cover a burst pipe?
A burst pipe is the classic example of a potentially covered water loss. If a supply line suddenly ruptures and releases water, the policy will often cover resulting damage to covered parts of the building and belongings, after the deductible and within the applicable limits. The NAIC’s February 8, 2024 consumer article describes this type of event as a “sudden and accidental” discharge.
What may be paid
Depending on the policy, covered damage can include wet drywall, flooring, cabinets, insulation, ceilings and other insured building materials. Personal property damaged by the released water may fall under the contents portion of the policy. If the home cannot be lived in during covered repairs, loss-of-use coverage may help with additional living expenses, subject to its terms and limits.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →What may not be paid
The policy may not pay to replace a pipe that failed because it was old, corroded or poorly maintained. It also may not pay for mold, rot or structural deterioration that accumulated before the sudden event, unless the policy provides a specific extension. The adjuster will separate direct, resulting damage from the maintenance issue that caused the release.
Sample wording is not universal wording
A sample HO-3 form hosted by the Insurance Information Institute contains coverage for accidental discharge or overflow of water or steam from within a plumbing, heating, air-conditioning or automatic fire-protective sprinkler system, or from within a household appliance. That sample is dated 1999. It illustrates how a policy can be written; it is not the wording of every current policy. Your own form and endorsements govern.
Rank #2

- Breakthrough 1804 ft Connectivity: Engineered with advanced Sub-1G long-range wireless tech, our leak detector maintains robust signals over unprecedented distances—reaching up to 1804 feet even through 5 dense walls. Secure every critical space in expansive properties, from deep basements to detached garages and distant outbuildings.
- Multiple Reminder Methods: Our water leak sensor supports multiple remote alarm. It can instantly send SMS, APP, and Email notifications to your phone (no matter how many times the SMS is used, it's free). Also, the water leak sensor flashes red and sounds a 105 dB alarm. Perfect for the basement, kitchen, or vacation home!
- Feature-Rich App: Receive instant push notifications. Use the “Find Device” feature to quickly trigger audible beeps to retrieve misplaced sensors. Add multiple email addresses through the APP, and your family and friends can also receive reminders when there is a water leak at home.
- Industry Leading IP67 Waterproof: Its IP67 waterproof rating ensures durability against spills, humidity, and accidental submersion.It can be used multiple times after wiping dry.
- Four-level volume adjustment: Customize your own alarm to fit your life! Use the app to adjust the volume in 4 levels, with a maximum alarm volume of 105 decibels. Whether it's day or night, whether it's in the bedroom or the basement, you can find the right volume.
Is a slow leak covered?
A slow leak is much less likely to be covered than a sudden rupture. Washington’s Office of the Insurance Commissioner explains that sudden leaks are usually covered while gradual leaks may not be. Insurers commonly ask whether the moisture developed over days, weeks or months and whether a reasonable homeowner would have noticed and repaired it sooner.
Why gradual damage is treated differently
Homeowners coverage is designed for fortuitous events, not predictable deterioration or deferred maintenance. A dripping supply line hidden under a sink, a pinhole leak inside a wall or a shower leak that slowly damages framing can create rot, mold and staining long before discovery. Policy exclusions may remove damage caused by repeated seepage, wear, deterioration, rust, corrosion or neglect.
Recommended Free Tools
Evidence that can affect the decision
- The date and circumstances of discovery.
- Whether there were earlier stains, odors, swelling, warped flooring or other warning signs.
- Plumber findings about the cause and likely duration.
- Maintenance, inspection and repair records.
- Steps taken after discovery to stop the source and prevent additional damage.
State rules and policy forms can change the result. Report the loss promptly even if you are uncertain; the insurer must evaluate the facts under the actual contract.
How are frozen-pipe losses handled?
Frozen pipes are often covered, but many policies condition coverage on reasonable precautions. NAIC guidance says a homeowner may need to maintain heat at a required minimum, insulate or otherwise protect plumbing, and shut off and drain water when a home is vacant, depending on the policy.
Check vacancy and temperature requirements
Read the conditions in the policy before winter travel or a vacancy. A policy may specify a minimum temperature or require that the water supply be shut off. Failing to follow a stated condition can give the insurer grounds to reduce or deny payment, even if the pipe itself froze unexpectedly.
Rank #3

- Leaking & Dripping: 2 water sensitive probes on the front for monitoring pipe/drain drip and 4 rear probes for detection water leak & floor moisture/flood. Both are work simultaneously, whatever leak sensors contact water, it will warning you in time.
- Loud & Mute: Our water leak alarm have loud and Mute Mode. It can emit 100 dB audio and loud enough to be heard even if leaks happened in basement. Press the button to mute the Water Detector Alarm when you arrived the flooded place.
- Tiny & Wireless: No Wire, Installation Required. Mini size allows you to put water leak alarms on any places, where the water leak may be happened. Such as house, underground, Pool, under Washing Machine, or unexpected disasters that may burst pipes, etc..
- Ultra Lifespan: Due to built-in 2*AAA Battery and energy-efficient circuit, our Floor Water Sensor Moisture Alarm has over 2 years standby time with Low Battery Alert, which reminds you to replace battery in time via flashing red light.
- Real IP66 Waterproof: The Water Alarm Detector is made of ABS & Stainless Steel, helps water sensor keep sensibility during the long time used without rust. Mounting Battery from the front to protect battery from getting wet and safer.
Separate the freeze from the maintenance issue
If a pipe freezes and bursts suddenly, resulting water damage may be covered. Damage caused by long-term lack of heat, an unrepaired defect or repeated seepage can be evaluated separately. Keep records of heating settings, winterization work and any emergency steps taken.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsDoes homeowners insurance cover flooding?
Ordinary homeowners insurance generally does not cover floodwater entering from outside. NAIC distinguishes covered plumbing or roof leaks from water caused by rain runoff, snowmelt, rising groundwater or similar outside sources. Those events generally fall within a flood exclusion.
What counts as a flood question
If water flowed across normally dry land, entered through a foundation or rose from an outside water source, do not assume a plumbing provision applies. The cause and path of entry matter. A roof leak caused by rain can be treated differently from rainwater that accumulates on the ground and enters through doors, walls or a basement.
Where separate flood coverage fits
Separate flood insurance may be available through the NFIP or a private insurer. Building and contents coverage, deductibles, waiting periods, exclusions and limits are governed by that separate policy. Review it before a storm rather than assuming the homeowners policy will fill the gap.
Is sewer backup covered?
Sewer or drain backup is not automatically the same as a sudden discharge from your interior plumbing. NAIC lists water-backup coverage as a separate type of homeowners protection and notes that outside sewer backup typically requires a rider or endorsement.
Rank #4

- High Sensitivity Leak & Drip Water Detections: Equipped with 4 bottom and 2 top high-sensitivity sensor probes. The adjacent bottom probes trigger the alarm once touching water, while the top probes may be activated by heavy humid mist. It precisely detects dripping water, minor water pooling and flooding on tile, wood, concrete and all flat surfaces, helping you prevent costly household water damage in advance.
- Long Lasting Power Supply: Comes with 10 durable AAA batteries for ultra-long standby use, no frequent battery replacement needed. It will sound an alarm and flash red LED once water leakage is detected. Built-in low battery reminder with red flashing light reminds you to replace batteries in time for uninterrupted leak monitoring.
- 0-120dB Adjustable Volume & Silent Mode: Support 4 adjustable volume levels from 0dB mute mode up to 120dB super loud alarm. Long press the TEST button freely switch volume as needed. You can easily mute the alarm after finding water leakage, when you at bedroom, kitchen and quiet living scenes.
- IP67 Full Waterproof & Dustproof: Built to withstand harsh conditions, this water sensor alarm leak detector is fully waterproof (IP67-rated allow short term immersion in water) and resistant to dust, Its durable structure and rust-resistant coating allow for long-term use, ideal for basements, laundry room, under kitchen sink,water pipe, beside the bathtub and washing machine.
- Easy Place Installation: No complicated wiring or extra tools required. Simply place the water sensor alarm in leak-prone areas, it will start 24-hour all-round automatic monitoring right away.
Read the endorsement, not just the policy summary
Look at the declarations page for a water-backup endorsement and then read its definition. Verify whether it covers sewer, drain, sump-pump overflow or some combination; whether cleanup and damaged contents are included; and whether a special deductible or sublimit applies. A policy can contain an endorsement with a limit far below the dwelling limit.
Do not confuse backup with flood
Water coming up through a sewer or drain may be handled under a backup endorsement. Water entering because an external waterway, storm surge or surface runoff inundated the property is generally a flood question. The physical appearance of the water is not enough; the source and policy definitions control.
Which parts of the policy can respond?
Homeowners policies divide protection into separate coverage categories. The same water event can affect more than one category, each with its own limit and deductible treatment.
| Coverage category | What it can address after a covered water event | Limits to check |
|---|---|---|
| Dwelling | Damage to the insured house, such as walls, ceilings, flooring and built-in cabinets. | Dwelling limit, covered-peril wording, exclusions and replacement-cost or actual-cash-value terms. |
| Other structures | Covered damage to detached structures such as a garage or shed, if the event reaches them and the policy covers the loss. | Separate other-structures limit and any special exclusions. |
| Personal property | Furniture, clothing, electronics and other belongings damaged by covered water. | Contents limit, category sublimits, valuation method and proof of ownership or condition. |
| Loss of use | Additional living expenses when covered repairs make the home uninhabitable. | Overall limit, reasonable period, receipts and whether the underlying loss is covered. |
Declarations pages show the limits selected for these categories. Endorsements can add, remove or modify coverage. A claim cannot be assessed accurately from the event description alone.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →What should you do immediately after water damage?
Prompt, safe action protects people and can prevent a covered loss from becoming worse. Washington’s insurance regulator advises reporting promptly and following the insurer’s recommendations.
Best Value

- Note: The sensor cannot be directly added to the app and a GoveeLife H5044 gateway is required(not compatible with H5040/H5043 gateway). With the kit "BB0DQLDBXWF", you can remotely monitor water leaks via your phone. "B0DQLDBXWF" is not included in the package.
- Ultra-Sensitive Detection: Equipped with 2 sets of sensor probes, ensuring early detection for basements, kitchens, bathrooms, and near appliances like dishwashers, water heaters, or washing machines. Protect your property from costly damage.
- Loud Alarm Sound With Customizable Volume: Maximize safety with a 105dB audible alarm that alerts you instantly to water threats. Customize alerts to 4 adjustable volume settings—ideal for quiet homes or noisy environments.
- 5 Years of Hassle-Free Operation: The water leak detector enjoys long-term protection with a built-in battery that lasts 5 years—no frequent replacements needed.
- IP67 Waterproof & Durable Design: Built to withstand harsh conditions, the water sensor with an IP67 waterproof rating ensures reliable performance in damp areas like under sinks, laundry rooms, or near sump pumps.
- Stop the source if it is safe. Shut off the appropriate valve or appliance supply and address electrical hazards before entering wet areas. Do not take a dangerous action to save property.
- Prevent additional damage. Use reasonable temporary measures and contact qualified emergency help when needed. Follow instructions from the insurer about mitigation.
- Notify the insurer or agent promptly. Give the date discovered, suspected source, areas affected and emergency steps already taken.
- Document the condition. Keep a written timeline, photographs or video, plumber reports, invoices and records of communications. Record which rooms, materials and belongings were affected.
- Review the policy while the facts are fresh. Check the declarations page, water-backup endorsement, deductible, limits, vacancy conditions and exclusions.
- Ask focused questions. Ask which coverage section applies, whether the deductible is separate, what limit controls and which parts of the repair are excluded.
Follow the insurer’s instructions about inspections and repairs. If the claim is disputed, request the explanation in writing and compare it with the cited policy language and applicable state requirements.
How insurers distinguish a covered event from maintenance
Claims decisions usually turn on causation and timing. The adjuster may ask whether the water escaped abruptly or accumulated gradually, whether the opening was caused by a covered event, and whether the homeowner took reasonable steps to maintain the property.
Questions that commonly matter
- Where exactly did the water originate?
- When did the discharge or seepage begin?
- Was there a prior stain, odor, swelling, mold or repair complaint?
- Did a storm create a roof opening, or did age and deterioration allow rain in?
- Was the home vacant, and were heat or water-shutoff requirements followed?
- Does an endorsement change the treatment of backup, mold or another excluded peril?
Reasonable mitigation after discovery is important, but it does not convert an excluded gradual leak into a covered sudden event. Conversely, an old component can fail suddenly; the resulting damage may still be covered even if the component itself is not.
Prevention and maintenance that reduce surprises
Insurance does not replace maintenance. Inspect supply hoses, valves, exposed pipes, roof areas and plumbing under sinks; address stains or damp odors promptly; and winterize a vacant property according to the policy’s conditions. A water-leak detector can be an optional way to notice a problem earlier, but regulator guidance does not endorse or test particular devices, and no detector guarantees prevention, discovery or claim eligibility.
Keep receipts and reports for plumbing repairs, roof work, winterization and emergency mitigation. These records can help establish when work occurred and what a contractor found, although they do not guarantee coverage.
What does the historical claims data show?
The Insurance Information Institute reported that about 22 percent of all homeowners insurance claims nationally in 2007 involved water damage, including frozen and burst pipes. That figure was published in 2009 and is historical; it is not a current claim share or a forecast of your risk. No newer directly comparable statistic is established here.
Common scenarios at a glance
| Scenario | Likely coverage question | Best next check |
|---|---|---|
| Washing-machine hose suddenly splits | Often a sudden and accidental discharge; resulting damage may be covered. | Confirm appliance/plumbing wording, deductible, limits and whether the hose replacement is excluded. |
| Dishwasher has leaked unnoticed for months | May be gradual damage and potentially excluded. | Document discovery and obtain a professional opinion on duration and cause. |
| Pipe bursts during a cold snap | May be covered if required heat and vacancy precautions were followed. | Check minimum-temperature, shutoff and winterization conditions. |
| Heavy rain enters through a storm-damaged roof | Roof-leak damage is typically covered, but the opening’s cause and maintenance history matter. | Determine whether a covered event caused the opening or whether wear and deterioration are excluded. |
| Basement fills after surface runoff | Generally a flood-exclusion issue under homeowners insurance. | Review separate NFIP or private flood coverage. |
| Sewer backs up into a bathroom | Often covered only if water-backup protection applies. | Check the endorsement, definition, sublimit and deductible. |
The practical answer is therefore conditional: sudden, accidental indoor releases are commonly covered for resulting damage; gradual leaks, neglected maintenance, outside flooding and sewer backup require closer policy-specific analysis. Read the declarations and endorsements, act quickly after a loss and ask the insurer to identify the exact coverage and exclusion it is applying.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

