Free tools Windows power users keep installed
One-click scans. No signup required.
A construction-linked payment plan releases money to a builder when defined work is completed or when documented work and costs reach an agreed point. It is not the same thing as a construction loan: the contract determines what you owe the builder, while the lender’s loan documents determine when borrowed funds are advanced. Before signing or authorizing a payment, match the claim to the contract, verify the work independently where possible, and check the building rules and insurance requirements in your jurisdiction.
What a construction-linked payment plan is
In a conventional purchase, the price is usually paid at settlement. A new build is different because the builder incurs costs over many months. A construction-linked plan spreads the contract price across deposits and progress payments tied to the project’s progress.
As an Amazon Associate I earn from qualifying purchases.
The payment trigger may be:
- a named stage, such as base, frame, lock-up or fixing;
- a specified date or interval; or
- work actually performed and costs incurred, supported by invoices, receipts or other records.
The signed building contract is the starting point. It should state the amount or percentage due, the event that makes it due, the documents required, and the procedure for approving a claim. Local legislation can restrict what a contract may require, but the exact rules differ by state, country, contract type and project value.
Do not treat an advertised “standard” schedule as universal. The Victorian and New South Wales examples below illustrate how regulators approach these arrangements; they are not a nationwide rule or a substitute for advice where the property is located.
#1 Best Overall
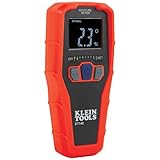
- WATER LEAK DETECTOR detects relative moisture content from leaks and flooding
- PINLESS MOISTURE METER measures relative moisture content in building materials
- NONDESRUCTIVE DETECTION up to 3/4-Inch deep using Electromagnetic field (EMF) technology
- USE ON DRYWALL, MASONRY, HARDWOOD, AND SOFTWOOD; calibrated for these materials only
- REVERSE-CONTRAST DISPLAY for easy viewing of reading and nine LED bars to indicate moisture range
Two different arrangements: builder payments and construction-loan draws
A builder’s progress claim answers, “Has the buyer become liable under the building contract?” A construction-loan draw answers, “Will the lender release part of the approved loan now?” Those decisions are connected but legally and operationally separate.
How a typical draw workflow operates
In the New South Wales MyHome Planner process, the builder issues an invoice, the buyer authorizes and signs it, and the buyer forwards it to the lender. Where a buyer has more than one construction loan account, the relevant account must be identified. The lender then applies its own valuation, documentation and release requirements.
- The builder submits a claim describing the stage or work performed.
- The buyer checks the claim against the signed contract and the physical work.
- The buyer signs or otherwise authorizes the invoice if it is valid.
- The authorized invoice is sent to the lender through the lender’s required channel.
- The lender confirms the draw, or asks for further evidence, before advancing funds.
A lender’s approval does not prove that the builder has completed a contractual stage. Conversely, a valid builder claim may still wait for a lender’s inspection or draw administration. Keep the contract due date and the lender’s submission deadline on separate calendars.
What a construction-permanent mortgage means in the United States
Consumer Financial Protection Bureau disclosure guidance treats the construction period and the permanent mortgage period as distinct phases for applicable construction-permanent loans. During construction, some loans use interest-only payments based on the amount advanced and the time that money remains outstanding. After conversion, the principal-and-interest payment, escrow disclosures or mortgage-insurance disclosures can change.
Rank #2
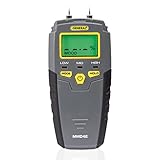
- HUMIDITY SENSOR: Our handy meter tool can quickly determine what level of remediation is needed to keep your family safe from black mold. High levels of dampness that go untreated are the leading cause of harmful fungus growth in the home.
- WATER LEAK DETECTOR: Finding the moisture content in your wood or drywall is the first step in early prevention. Continuously check and test suspicious water stains around the house so you can determine whether the area is wet or has already dried. Low, medium and high moisture tones and on-screen icons, Reading HOLD button
- MOISTURE READER: The mold test features large 0.3" high digits in a backlit LCD for quick and easy detecting. Our mildew scanner includes extra 8mm stainless steel pins, a protective cap that doubles as a calibration checker, and a “9V” battery.
- MOLD TESTER: For an accurate test read, stick the stainless steel pins into the surface of what you're measuring. The gauge has a broad range of 5 - 50% for wood and 1.5 - 33% for building materials such as concrete and drywall.
- GENERAL TOOLS: We're a recognized leader in designing and developing specialized precision tools dedicated to delivering exceptional customer service. We encourage artisans and DIYers to work smarter, measure better, and repair more productively.
That US disclosure framework explains financing costs; it does not create a builder’s stage schedule. A US borrower still needs to read the construction contract, draw conditions and lender agreement together.
How payment triggers are written
Completed-stage schedules
A completed-stage schedule assigns a fixed amount or percentage to an objectively described stage. Victoria guidance gives domestic building examples including the base, frame, lock-up and fixing stages. The contract should define what must be finished, not merely name a date. “Frame” might need to specify structural framing, roof framing or related inspections so that both sides can identify completion.
Work-and-cost schedules
New South Wales guidance also describes schedules linked to work performed and costs incurred. Such a claim should be supported by the records required by the contract, such as invoices, receipts, subcontractor statements or a progress report. The buyer should be able to see how the amount requested was calculated and which work it relates to.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →| Schedule type | Payment trigger | Evidence to request | Main question for the buyer |
|---|---|---|---|
| Completed stage | The defined stage is finished | Site inspection, plans, contract checklist and any required surveyor approval | Is every contractual element of the stage complete? |
| Work and costs incurred | Specified work has been performed and eligible costs incurred | Invoices, receipts, progress records and the contract’s calculation | Do the documents support the amount and the work claimed? |
| Date or interval | A calendar date or agreed period arrives | Contract wording plus evidence that any stated work condition has been met | Does the contract make time alone sufficient, or is completion also required? |
If the wording is ambiguous, do not resolve it by paying first and arguing later. Ask the builder to identify the exact clause and obtain advice from a building lawyer, regulator or lender before the contractual response deadline.
Rank #3

- WOOD MOISTURE METER: Prevent water and moisture build-up with our humidity reader. It can quickly determine what level of remediation is needed to keep your family safe. High levels of dampness that go untreated can cause hazardous living conditions.
- PROTECT YOUR WORK SURFACE: This tool has no pins, so it won't mar, scratch, or damage walls. It features auto-calibrating, a 2" diagonal backlit LCD screen, a 3-color LED bar graph, a hold button, and an audible alert for fast and accurate detection.
- DEEP READER: It can read the levels up to 3/4" (19mm) deep into the surface with a broad measurement range of 0 to 53% for softwood, 0 to 35% for hardwood, and relative readings for wallboard, drywall, and masonry.
- MOLD DETECTOR: Early prevention is vital when stopping mold formation. Check and test suspicious water stains around the house to determine if the area is wet or has already dried. It includes an out-of-range alarm and a low 9V battery alert.
- GENERAL TOOLS: We have been a recognized leader in the innovation, design, and development of specialized precision tools for many years. We encourage craftspeople, artisans, and DIYers to work smarter, measure better, and increase productivity.
What to verify before signing the contract
Read the payment schedule with the plans
List every payment trigger, its amount, the permitted timing, and the evidence required. Check that the schedule matches the scope of work and that no large amount is due before substantial visible work. Ask how variations, provisional sums, delays and defective work affect the next claim. Confirm whether the contract allows a claim for stored materials and what proof is required.
Check the builder and statutory cover
Verify the builder’s registration or licence with the local authority. Confirm the required home-building compensation or domestic building insurance before paying where local law requires it. New South Wales guidance says required cover must be taken out and a certificate provided before a contractor asks for a deposit or another contract payment. Check that the certificate identifies the correct project, parties and contract value.
Consider an independent contract review
A building lawyer can identify an unusually front-loaded schedule, unclear stage definitions, broad variation rights or a payment clause that conflicts with local law. An independent building consultant or inspector can help define objective completion evidence before work starts.
Deposits and stage percentages: jurisdiction-specific examples
Deposit caps and stage percentages do not travel across borders. Use the following figures only as examples of the rules published in each jurisdiction, and recheck the current law before signing.
Rank #4

- Wood Moisture tester: Detects moisture in walls, wood & masonry with a maximum sensing depth of 0.75 inches. User-friendly for contractors and homeowners, perfect for home inspections and damp testing.
- Prevent Water Damage Early:Identify moisture caused by leaks, flooding, or high humidity in time. Ideal for home inspection, renovation, and DIY repairs.
- For reliable results, avoid metal pipes, wiring, or steel studs, which may interfere with signals. Includes simple, step-by-step guidance for testing different materials
- Accurate Readings – Avoid Metal Surfaces:For best results with this moisture reader for walls, keep away from metal objects to avoid interference and ensure accurate readings
- The pinless sensor measures moisture without leaving holes or marks, making it safe for finished floors, painted walls, tiles, furniture, and sensitive materials.
| Jurisdiction and source | Published rule or guidance | How to use it |
|---|---|---|
| Victoria — Consumer Affairs Victoria | For covered domestic building work, the deposit cannot exceed 10% for contracts under AUD 20,000 or 5% for contracts of AUD 20,000 or more. Guidance also lists stage schedules for certain contract scopes and says buyers pay for completed stages. | Applies to the Victorian work and contract types covered by that guidance; the retrieved page metadata did not state a publication year. |
| New South Wales — NSW Government, 2026 | A builder can seek a maximum 10% of the total contract price as a deposit before work commences. The guidance cautions buyers to ensure required home-building compensation cover is in place first. | Applies to the relevant NSW contracts and current law; the page was reported as published in September 2026. |
Consumer Affairs Victoria states: “Before you make each progress payment, check the work.” In the NSW MyHome Planner guidance, the warning is: “Your builder cannot ask for any progress payment in advance of the work being carried out.” Both statements are jurisdictional consumer guidance, not a universal contract rule.
A pre-payment checklist for every claim
Use the same controlled process for the deposit, each progress claim and the final account.
- Identify the trigger. Write down the contract clause, stage name or work interval cited on the invoice.
- Recalculate the amount. Check the percentage, agreed price, approved variations, credits and any previous payments. Make sure the cumulative total does not exceed the contract price without a documented variation.
- Inspect the site. Compare the actual work with the plans, specifications and stage definition. Photograph relevant areas and record the inspection date.
- Confirm required approval. Victoria advises checking that the work meets the contract and has passed the building surveyor’s inspection. Arrange an independent consultant or inspector when you cannot confidently assess the work yourself.
- Request supporting records. For a work-and-cost claim, obtain the invoices, receipts or other documents required by the contract. Ask the builder to explain any discrepancy in quantities or rates.
- Check insurance or compensation cover. Confirm that the certificate covers this project and that the payment will not be made before a legally required certificate is issued.
- Follow both authorization paths. Sign or approve the builder’s claim only after your checks, then submit it to the lender exactly as required. Retain the signed invoice and draw confirmation.
- Record the decision. Keep the claim, inspection notes, photographs, correspondence, receipts, approvals and bank or loan records together.
Why early or extra payments are risky
Paying before the specified work is complete shifts risk to the buyer. If the builder delays, abandons the project or becomes insolvent, money paid for unfinished work can be difficult to recover. Victoria warns that excessive deposits can contribute to costly disputes and that advance payments may not be covered by domestic building insurance. New South Wales warns that an unauthorized early or additional payment may affect recovery under home-building compensation cover if the builder becomes insolvent.
Recommended Free Tools
Do not agree to an “off-schedule” payment merely because the builder says it is needed to keep trades on site. First check the variation clause, the contract schedule, the lender’s conditions and the applicable compensation policy. Obtain written advice promptly if the builder threatens suspension or refuses to provide evidence.
Best Value

- Moisture Meter for Home Inspection: Quickly identifies moisture from leaks, flooding, or humidity in basements, bathrooms, kitchens, and wood—perfect for home inspectors and DIY repairs
- Prevent Water Damage Early:Identify moisture caused by leaks, flooding, or high humidity in time. Perfect for home inspection and maintenance to help you avoid expensive repairs and long-term structural issues
- Built-in Flashlight for Dark Areas:Inspect crawl spaces, attics, or behind cabinets with ease using the integrated LED flashlight—great for real estate and renovation use
- Accurate Readings – Avoid Metal Surfaces:For best results with this moisture reader for walls, keep away from metal objects to avoid interference and ensure accurate readings
- Safe for Multiple Surfaces:The non-destructive sensor works on wood masonry, concrete, and more. No drilling or pinholes required—great for finished surfaces and sensitive materials
What to do when a claim is incomplete or disputed
Ask for a written explanation
Identify the missing work or document and state the contract clause you believe applies. Request a corrected claim or a completion date. Keep communications factual and dated.
Do not simply ignore a formal claim
Progress-payment and security-of-payment laws can impose short response periods and consequences for late payment. NSW Legal Aid describes procedures for responding to payment claims, but the deadline depends on the contract and applicable law. If a claim is formally served, obtain local legal advice immediately rather than allowing a response period to expire.
Separate undisputed and disputed amounts
Where the contract and local law permit, ask the builder or adviser whether an undisputed amount can be paid while the balance is assessed. Never invent your own split or withhold the entire amount without checking the applicable procedure; doing so can create default or adjudication risk.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
How to compare two proposed payment plans
When builders offer different schedules, compare the plans on the same document rather than choosing the one with the lowest deposit alone.
| Comparison point | Questions to ask |
|---|---|
| Trigger | Is payment tied to a completed stage, a date, or documented work and cost? |
| Stage definition | Can an independent person verify completion from the plans and specifications? |
| Front-loaded exposure | How much is paid before visible, inspectable work exists? |
| Evidence | Are inspection approvals, invoices and receipts required? |
| Variations and delays | Who approves a variation, and can a disputed variation be added to the next claim? |
| Insurance eligibility | Does each payment comply with the project’s compensation or domestic building insurance conditions? |
| Loan mechanics | When does the lender inspect, release funds and begin charging interest on each draw? |
Keeping control during a long build
Nominate one person to approve claims and use a consistent file naming system for invoices, photos and approvals. A simple moisture meter or camera can help you record observations during a site visit, but a consumer tool does not certify that a stage is complete. Official guidance supports using an independent building consultant or inspector when specialist judgment is needed.
At each lender draw, reconcile three figures: the builder’s cumulative claims, the amount the lender has advanced, and the remaining contract balance. Ask the lender how undrawn funds, interest-only construction payments and the permanent-loan conversion will be handled. A draw statement is a financing record, not a substitute for the builder’s contractual invoice.
Rules that depend on where you build
The examples in this article come from Victoria and New South Wales in Australia and from US CFPB mortgage-disclosure material. Deposit caps, insurance certificates, inspection requirements, payment deadlines, security-of-payment procedures and lender disclosures may be different elsewhere. Before signing or paying, check the regulator for the property’s location, the exact contract form, the loan documents and the current insurance requirements. If those documents conflict or a claim appears early, get advice from a locally qualified building lawyer, inspector, regulator or lender before the deadline expires.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

