What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Keep a document trail for every construction-material purchase that shows what you bought, from whom, when, for how much, whether sales or use tax was paid or claimed exempt, and which job or inventory record explains its use. Then reconcile that trail to the applicable state tax return. The records you need and the tax result depend on the state and the facts of the purchase and contract; there is no single nationwide contractor rule or retention period.
Build a record trail from purchase to tax return
A useful recordkeeping system answers two different questions: what happened to the materials, and what happened with tax? An invoice may identify a purchase but not explain where the materials went or why tax was not charged. A job-cost entry may identify a project but not prove that sales tax was paid. Keep the documents and accounting records that connect these facts.
As an Amazon Associate I earn from qualifying purchases.
For each purchase, aim to be able to trace this chain: supplier document → tax status and evidence → job or inventory destination → accounting entry → return treatment. The chain can be maintained in paper files, an accounting system, or a combination. California’s Department of Tax and Fee Administration (CDTFA) specifically lists “Purchase invoices, especially out-of-state purchases” and “Job cost folders” among contractor records. Illinois audit guidance describes auditors reviewing direct-purchase invoices, inventory withdrawals, job-cost records, and general-ledger or accounting records. That Illinois description is an example of audit review, not a universal required filing format.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallStart with one purchase log
Use a purchase log, accounting entry, or equivalent record that can be searched and reconciled. A practical log can include the following fields; it is an organizing tool, not a state-prescribed form:
#1 Best Overall
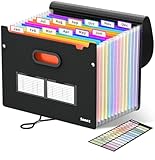
- Superior Durability: Featuring strong 100C thickened cover and reinforced edges, surpassing competitors in durability. Made from PVC-free, acid-free materials, ensuring secure organization of bills and documents while delivering unparalleled durability and reliability
- Deeper Pockets & Unobstructed Tabs: In response to a common issue in accordion folders where papers cover index labels, we've increased pocket height by 0.8 inches (2 cm). This unique enhancement ensures your labels remain visible—a feature unmatched by competitors
- Ample Capacity Monthly Bills Organizer: Our expandable monthly bill organizer can extend up to 14 inches, accommodating over 1500 sheets files while standing stable. With 12 pockets, it's perfect for storing tax records, bills, receipts, invoices and important family files for over a year
- Sticky Labels & 3 Loops Bungee Closure: Colorful monthly tabs and labels help you locate the target object at a glance and manage monthly tasks with ease. The elastic band closure with three loops expands generously to accommodate all your storage needs
- Unlock Versatile Organization: Whether at home, in the office, or on the go, it offers flexible organization for invoices, medical finance records, and identification documents, ensuring efficiency wherever you need it
| Field | What to capture | Why it helps |
|---|---|---|
| Purchase identity | Supplier name, invoice or receipt number, and purchase date | Lets you locate the source document and distinguish one transaction from another. |
| Materials and amount | Description or item detail, quantity where shown, purchase price, and any separately shown sales tax | Shows what was acquired and the transaction amount reflected in the supplier record. |
| Tax status | Tax charged by supplier, tax paid directly, no tax charged, or exemption claimed | Flags purchases that may need review before filing and identifies the evidence to retain. |
| Destination | Project name or number, inventory location, or other disposition record | Connects the purchase to its eventual use rather than leaving it as an unassigned expense. |
| Supporting reference | Link or file name for invoice, contract, delivery record, exemption support, or tax payment proof | Makes the explanation verifiable without relying on memory. |
| Accounting and return period | Relevant job-cost, inventory, general-ledger, and tax-return period references | Supports reconciliation between the purchase, project records, and reported amounts. |
Record the facts shown by the documents rather than assuming the invoice answers every tax question. If the seller charged tax, retain the invoice showing it. If no tax appears, record that fact and keep the contract, exemption documentation, or other relevant support that explains the transaction. Whether a particular tax treatment is correct is a state-specific question; the log is not a substitute for that determination.
Use a consistent filing convention
Give each document a predictable home. For example, file it by tax year and supplier, then cross-reference the project or inventory record in the purchase log. A digital folder structure might use year, supplier, and invoice number; a paper system might use separate job folders plus a central purchase file. Either can work if staff can retrieve the original documents and the project connection. Keep the supplier invoice or receipt even if the same amount also appears in bookkeeping software.
Do not treat an optional organizer, filing method, or accounting platform as a legal requirement. What matters for the record trail is that supporting documents remain legible, accessible, and connected to the transaction. The official guidance cited here does not require paper storage or endorse a particular product.
Free tools Windows power users keep installed
One-click scans. No signup required.
Keep the documents that explain the transaction
Invoices are central, but supporting records can be necessary to explain who bought the materials, how the contractor treated them, where they were delivered, and why tax was or was not paid. Retain records relevant to the actual purchase and project rather than saving only a total from the books.
Supplier and payment records
- Keep the invoice, receipt, or other purchase document with the vendor, date, materials, price, and sales tax shown, if any.
- For out-of-state purchases, make the invoice easy to identify. CDTFA specifically calls out purchase invoices, especially those for out-of-state purchases.
- Keep evidence supporting tax paid or a claimed exemption. Depending on the transaction, that may include supplier documentation or records of a direct tax payment.
- Retain purchase contracts or other billing documents when they clarify the agreed transaction or the party responsible for providing materials.
Delivery, project, and accounting records
- Connect the invoice to a job-cost folder or equivalent project record. California names job-cost folders in its contractor recordkeeping list.
- Keep delivery records, bills of lading, or receipt records when they help identify what arrived and where it went. Wisconsin describes maintaining inventories, purchases, receipts, invoices, bills of lading, and pertinent accounting records for contractors required to hold the specified permits or certificates.
- Keep inventory records and withdrawal records when materials are purchased into inventory and later assigned to a job. Illinois audit guidance mentions inventory withdrawals as one record type auditors may review.
- Retain relevant in-progress and final billing records. California includes both in its list of contractor records.
- Preserve the corresponding general-ledger or accounting record so the transaction can be followed from source document to books. Illinois describes those records in its audit guidance; it does not establish one mandatory format for every contractor.
Exemption and nontaxable-treatment support
When a purchase is treated as exempt or otherwise nontaxable, keep the records that establish the basis for that treatment. California identifies documents supporting nontaxable purchases or sales as records contractors should keep. Wisconsin’s listed records also include pertinent accounting records and inventory-related documents for contractors subject to the stated permit or certificate requirements. The exact document needed depends on the state rule and transaction; do not assume that writing “exempt” on an invoice is sufficient proof.
Rank #2

- Expanding file folder in Black with flap and cord closure for organizing and securing 8.5 x 11-inch letter-size documents
- Holds up to 260 sheets; 13 pockets for easy subdividing; each pocket expands to 7/8-inch
- Archival quality, acid free, and PVC free
- Waterproof and tear resistant
- Made of durable poly material
Track who supplied the materials and where they went
Material records should distinguish a contractor purchase from an owner-furnished item, an inventory item, and a direct purchase assigned to a job. Those categories can change the tax analysis and the evidence needed. Use the contract and project records to capture who acquired or furnished the materials, and keep a record of how they were used or accounted for.
Materials purchased by the contractor
Record the purchase under the supplier document and assign it to the job or inventory. If the supplier charged tax, retain the invoice that shows the charge. Michigan Treasury’s building-contractors bulletin gives an example in which contractors are not liable for use tax on building materials when they maintain receipts, invoices, and/or contracts demonstrating that sales tax was paid. The bulletin’s example depends on its stated facts; it is not a universal rule for every state or transaction.
Materials bought for inventory, resale, or later use
Do not let an initial purchase classification disappear when the material is eventually taken from stock. Preserve the purchase entry, the inventory record, and the withdrawal or job assignment so the later use can be explained. Minnesota guidance illustrates that materials bought exempt and later used in a construction contract may need to be reported as use-tax purchases under Minnesota’s rules. That example is state-specific: the fact that a purchase was initially exempt does not by itself establish how another state treats later use.
Materials furnished by the project owner
Record owner-furnished materials separately from the contractor’s supplier purchases. Retain the contract or project record identifying the arrangement and any evidence relevant to tax paid on those materials. South Dakota’s Department of Revenue says contractors owe use tax on furnished project material when they lack documentation showing sales or use tax was paid; examples of documentation include an invoice showing tax or an owner’s written statement. This describes South Dakota guidance, not a nationwide presumption about owner-provided materials.
Check tax status before you file
Use the purchase records to identify which transactions need attention, then apply the rule for the jurisdiction governing the work. A recordkeeping workflow should not automatically treat every material purchase as taxable, or every invoice with no tax line as proof that no tax is due. The contractor’s classification, contract, source of materials, tax paid, exemption or inventory treatment, and state rules can all matter.
Rank #3

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
Review purchases in four practical groups
- Tax shown as paid to the seller. Confirm the invoice identifies the relevant purchase and tax charge; retain it with the project or inventory reference.
- Tax paid directly. Keep the payment and reporting record that supports the direct payment, and connect it to the purchase so the same transaction can be reconciled.
- No tax shown or charged. Flag the purchase for a jurisdiction-specific review. Determine whether tax should be self-reported or whether another treatment applies, and retain the relevant contract, delivery, exemption, or other supporting documents.
- Exempt, resale, inventory, or owner-furnished treatment. Keep the documents that support the original treatment and the later disposition or use, if any. Do not assume the initial classification resolves tax when materials are later used on a job.
This grouping is an internal review aid, not a legal conclusion. California directs taxpayers to report purchases subject to use tax on the return, while Minnesota’s guidance illustrates a state-specific case in which materials bought exempt and later used in a construction contract may become reportable use-tax purchases. Determine the treatment under the relevant state’s current instructions.
Reconcile source documents, job records, and returns
Before filing, compare the purchase log with the supplier documents, job-cost or inventory records, and general ledger. Check that purchases subject to use tax are reflected in the reported amount and that tax already paid or an exemption claim has supporting evidence. Resolve unmatched items rather than forcing them into a tax category because the accounting period is closing.
- Look for purchases with no invoice attached, missing tax status, or no job or inventory assignment.
- Investigate invoices showing no tax, especially when the purchase was from out of state or was initially coded exempt.
- Check whether inventory withdrawals and owner-furnished materials are represented in the records used for the applicable return.
- Confirm that tax-paid purchases are not mistakenly treated as unpaid without considering the jurisdiction’s rules and the evidence available.
- Keep a note of corrections or decisions with the source documents so a later reviewer can understand what changed and why.
The purpose is not to make every state’s reporting form look alike. It is to make the figures on the return traceable to transactions and to preserve the facts that explain their treatment.
Retention periods depend on the jurisdiction
Keep records for the period required by the state or local authority applicable to the work, and verify the current requirement rather than adopting one number for all projects. The examples below differ and are not a nationwide standard.
| Jurisdiction and source | Retention information stated | How to use the example |
|---|---|---|
| Connecticut Department of Revenue Services, building-contractors publication from 2018 | At least six years | The publication is dated 2018; check current Connecticut instructions or law before relying on it as present-day advice. |
| Nevada Department of Taxation, construction guidance page; publication date not stated | Four years | The page lists purchase invoices, sales journals, general ledgers, job files, and other records. Confirm current Nevada requirements for the situation. |
These figures demonstrate why a contractor working across state lines should not set one retention rule based on a neighboring state’s guidance. A practical policy can use the longest applicable period among the jurisdictions and other obligations affecting the business, but confirm the applicable legal requirements with the relevant authority or qualified tax adviser. Keep the underlying records organized for the full applicable period, not merely until a return is filed.
Rank #4

- Stable & sturdy construction: Expanding file folder is made from durable wipe-clean polypropylene. Acid-free and high-quality for using trustingly. Waterproof & sturdy enough to keep the file organizer from collapsing. The accordion folder's cord closure and adjustable flap provide additional security. Built-in file separation layers are flexible to ensure the files don't wrinkle.
- Handy organization & Easy lookup: Expandable file folder has 24 pockets designed for keeping our paperwork organized. Accurately classified storage in the specific color slot and labeled with tabs, so it is easier to find the papers what is needed.
- Plentiful storage: Product Size: 13'' L x 9.25'' H. Each pocket fits well for all A4/Letter size paper. Excellent scalability. The accordion file folder can be stretched pretty far, more than 24 inches. 24 pockets allow you to store more than 4000 sheets of paper documents.
- Portable & stylish: Classic lightweight folder organizer can be compressed to a minimum thickness of about 2 inches, so it can be held up great for traveling to and from all different locations for work. Fits perfectly when completely closed in the file cabinet. The dividing sections of the rainbow file folders come in six bright colors, stylish and beautiful. Versatile document organizer for home, office, school, and travel scenarios, compact and light.
- Expandable desktop folder: Folders can be expanded to different widths as the number of files you put into increases. Stand on its own on the desk and not easy to tip over when pulled out to maximum capacity and filled. Each pocket is completely sealed at the bottom to keep small objects do not move.
State examples are not interchangeable
The term “use tax” appears in multiple state systems, but that does not mean contractors are classified or taxed identically. Before applying a rule, identify the state or states involved, how that state treats the contractor and the materials incorporated into real property, whether sales tax was paid, and what event triggers reporting or liability. State guidance below illustrates distinct points rather than a single national answer.
| Jurisdiction | What the cited guidance says | Recordkeeping implication |
|---|---|---|
| California | CDTFA names purchase invoices, especially out-of-state purchases; job-cost folders; in-progress and final billing records; and documents supporting nontaxable purchases or sales. It also directs taxpayers to report purchases subject to use tax on the return. The page says contractors not required to hold a seller’s permit whose annual gross receipts are $100,000 or more must register for a Consumer Use Tax Account; recheck the current threshold and applicability. | Maintain source invoices and job-level supporting records, and verify current registration and reporting instructions for the contractor’s circumstances. |
| Michigan | A Department of Treasury bulletin approved December 10, 2025, and updated September 17, 2026, describes Michigan use tax as 6% of the purchase price unless tax was already paid at the relevant amount or an exemption applies. Its building-material example relies on receipts, invoices, and/or contracts demonstrating sales tax was paid. | Keep tax evidence with the transaction. The stated rate and example are Michigan-specific and should not be generalized to another jurisdiction. |
| Minnesota | Guidance illustrates that materials bought exempt and later used in a construction contract may need to be reported as use-tax purchases under Minnesota rules. | Maintain an inventory trail from the exempt purchase through withdrawal and project use, then review the state reporting rule. |
| South Dakota | Guidance says use tax is owed on furnished project material when documentation showing sales or use tax was paid is lacking; an invoice showing tax or an owner’s written statement are examples. | Keep evidence for owner-furnished materials rather than recording only contractor purchases. |
For an unfamiliar jurisdiction, first establish how it defines the contractor’s role and transaction. Alabama Department of Revenue’s FAQ “Who is a contractor?” reflects this threshold issue: classification should be determined before assuming a tax result. Do not import California’s registration threshold, Michigan’s stated rate, South Dakota’s owner-material example, or a retention period from another state into a different state’s filing.
Prepare a file that can answer an audit question
A well-kept file lets someone who did not make the purchase reconstruct it without relying on the contractor’s memory. The documents should tell a consistent story from acquisition through use and reporting.
For each questioned purchase, be ready to locate
- The invoice, receipt, or contract showing the supplier or furnishing party and purchase details.
- Evidence of sales tax charged, use tax paid, or the support for an exemption or other treatment.
- The project, inventory, or delivery record showing how materials were handled.
- The accounting entry and, where relevant, the return period to which the transaction was assigned.
- Any related billing record or written statement that explains an owner-furnished or other atypical arrangement.
This is a retrieval checklist, not a claim that every jurisdiction requires every item in every case. Preserve what is relevant to the transaction and applicable state rules. If a key document is missing, identify the gap and consult the jurisdiction’s guidance rather than reconstructing a tax-paid claim from assumption.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteSet up a repeatable routine
A small routine at purchase time is easier to sustain than a year-end search for records. Assign responsibility for capturing documents and reviewing exceptions, especially when purchasing, project management, and bookkeeping are handled by different people.
- At purchase: save the supplier document and record vendor, date, materials, amount, and tax shown.
- When assigning materials: connect the purchase to a project or inventory entry; record owner-furnished materials separately.
- When tax status is unclear: flag the item for review and retain the contract, delivery, exemption, or payment evidence relevant to the question.
- During periodic bookkeeping: compare purchases and inventory activity with job-cost and accounting records; follow up on missing documents and unassigned materials.
- Before each return: reconcile transactions subject to use tax, tax already paid, and claimed exemptions to the records used for filing.
- After filing: retain the return support and underlying purchase records for the period required in each applicable jurisdiction.
The result is a record system that supports both routine reporting and questions that arise later: a transaction can be found, its destination explained, and its tax treatment traced to evidence and the rule for the state involved.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.