What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
HouseAmp, a fintech platform for home improvement, reportedly raised $12.4 million to expand a system that connects homeowners, real estate agents, lenders, and service providers around repair and remodel work. For homeowners, the useful takeaway is not simply that another financing option exists. The bigger point is that more companies are trying to solve the same problem we see every week in construction: people need work done before they have clean access to cash.
That can be a good thing. A roof leak, unsafe electrical panel, failed HVAC system, rotten siding, dated kitchen, damaged flooring, or inspection repair list can stop a sale or make a home harder to live in. Financing can help a homeowner move faster. But financing is not project management. Borrowed money does not write a scope, pull a permit, verify a contractor’s insurance, protect against liens, or make a bad change order disappear.

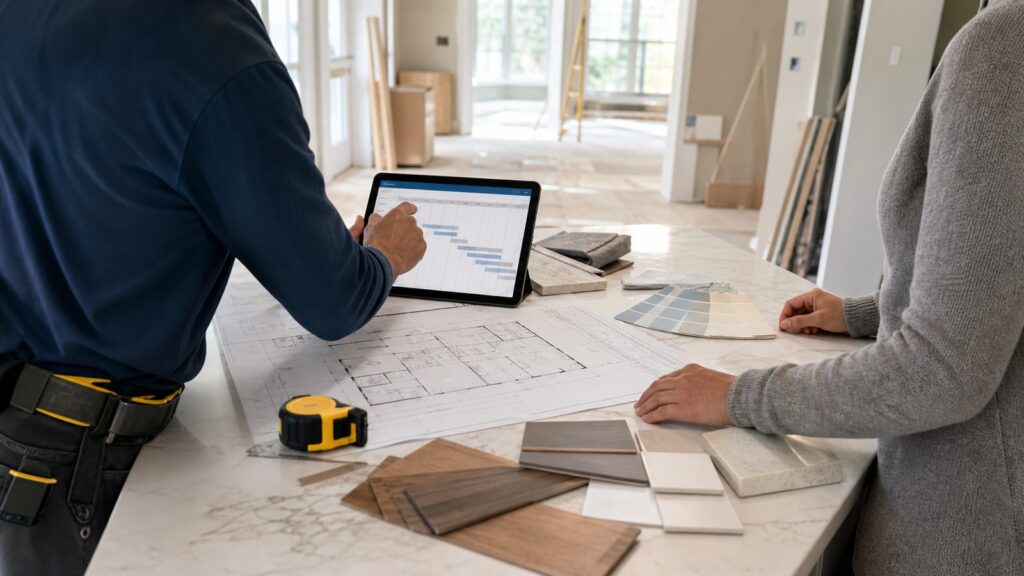
On our job sites, the projects that go well usually have the same bones: a written scope, realistic pricing, permit planning, milestone-based payments, clean communication, and a contractor willing to say no when the scope is wrong for the house. The projects that get expensive usually start with a vague budget and a deadline that assumes nothing will go wrong.
This guide explains what HouseAmp-style home improvement financing means for homeowners in 2026, what remodels actually cost, where the risk sits, and how to use financing without putting your equity, closing date, or property condition at unnecessary risk.
Recommended Free Tools
#1 Best Overall
HouseAmp in Plain English
HouseAmp was founded in 2020 and built lending and payment infrastructure for homeowners, agents, lenders, and home service providers. The reported $12.4 million raise included investors such as Third Prime and Fortress Private Equity. The platform sits in a growing lane: helping homeowners fund repairs or improvements, often when the work is tied to selling, buying, refinancing, or preserving property value.
For a homeowner, that may look like financing a pre-listing punch list, repairing items found during inspection, replacing worn finishes before showings, or tackling repairs that make the house safer and more marketable. For agents, lenders, and contractors, the appeal is speed and coordination. A deal can fall apart when the seller cannot pay for required repairs, the buyer does not want a credit, and the contractor needs deposits before starting.
The construction side is where the fine print matters. A financing platform can help move money, but it cannot know whether your 1975 bathroom has hidden rot behind the tile, whether your attic ventilation is undersized, whether your panel has capacity for new circuits, whether your local building department requires plan review, or whether your property falls inside a floodplain substantial-improvement threshold.
That is why homeowners should treat platforms like HouseAmp as one part of the process. Useful, yes. Complete, no. The money should follow the construction plan, not the other way around.
The 2026 Remodeling Market Is Still Active, But Tighter
The timing matters. Home improvement demand is still strong, but it is not the easy-money remodel market of a few years ago. Harvard’s remodeling indicator projected owner-occupied home improvement and repair spending to keep growing but slow through 2026, with growth easing toward 1.6 percent and spending around $518 billion by year-end in its January 2026 release. Its July 2026 outlook pointed to momentum continuing to slow into mid-2027.
NAHB’s second-quarter 2026 Remodeling Market Index was 61. That remains above the 50 mark that separates positive from negative territory, and the index has held in the low 60s over the past year. In practical terms, remodelers are still busy, but homeowners are becoming more selective and price-sensitive.
Material pricing is another pressure point. NAHB reported that 74 percent of remodelers said suppliers increased material prices since March 2026 because of higher fuel costs. The average materials increase was 6.7 percent. On a $40,000 project, a 6.7 percent material increase does not mean the whole job rises by exactly $2,680, because labor, overhead, subcontractors, permits, and margin all interact. But it does mean a quote written in March may not be reliable in August if material selections were not locked.
New construction also affects remodeling. U.S. Census June 2026 residential construction data showed privately owned housing permits at a seasonally adjusted annual rate of 1.367 million, down 3.0 percent from May and 2.3 percent from June 2025. When new-home supply is constrained or expensive, more owners improve what they have. That keeps pressure on skilled trades, inspection calendars, and lead times for cabinets, windows, roofing, mechanical equipment, and specialty finishes.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Financing Helps, But It Does Not Replace a Construction Scope
The most dangerous remodel budget is the one built from a sentence. “We need to update the kitchen” is not a scope. “Repair the house before listing” is not a scope. “Make the bathroom nicer” is not a scope. Those are goals.
A usable construction scope identifies rooms, surfaces, systems, quantities, exclusions, permit responsibility, inspections, materials, allowances, schedule assumptions, and how surprises will be priced. Before applying for financing, a homeowner should know whether the project is a cosmetic refresh, a repair project, a code correction, a structural renovation, or a resale-prep package.
On our jobs, we want the financing amount to match the real scope. That means labor, materials, permits, disposal, protection, cleanup, contingency, and final inspection. If the borrower funds only the pretty part of the job, the ugly part still comes due. Water damage, panel upgrades, framing corrections, exhaust venting, and rotten sheathing do not care what the original loan application said.
A good pre-financing review should include a walk-through by a licensed contractor, photos of existing conditions, a written estimate, clear alternates, and a contingency recommendation. For ordinary cosmetic work, a 10 percent contingency may be enough. For older homes, concealed plumbing, plaster, foundation movement, termite damage, or past unpermitted work, 15 to 25 percent is more realistic.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWhat Remodels and Repairs Cost in 2026
National averages are only a starting point. Labor rates in Dallas, Tampa, Phoenix, Chicago, Seattle, and rural markets can vary widely. So can permit fees, disposal costs, access conditions, union rules, storm-code requirements, and material availability. Still, the 2026 numbers below give homeowners a useful planning range before they borrow.
| Project Type | 2026 Cost Range or Average | What Usually Drives the Price |
|---|---|---|
| Whole-home renovation | Average around $52,133; broad range of $3,000 to $190,000 | Rooms affected, square footage, structural changes, finish level, trade count, local labor |
| Major repairs or renovations | $4,212 to $25,431 | Roofing, foundation, plumbing, electrical, water damage, access, emergency timing |
| Kitchen remodel | Average around $26,942; typical range $14,589 to $41,547 | Cabinets, layout changes, countertops, flooring, appliances, lighting, electrical circuits |
| Bathroom remodel | Commonly $8,000 to $45,000; midrange averages near the mid-teens | Waterproofing, tile quantity, plumbing relocation, ventilation, fixtures, accessibility upgrades |
| Full home remodel | Often $100,000 to $350,000+; luxury or structural work can exceed $500,000 | Structural scope, kitchens and baths, mechanical systems, windows, exterior envelope, finishes |
| Building permits | Often $150 to $3,000; typical guides show $525 to $3,114, with complex renovations up to about $8,500 | Local fee schedule, project valuation, plan review, trade permits, reinspections, certificate requirements |
These ranges should not be used as a substitute for a site-specific estimate. For example, a $16,000 bathroom remodel may be reasonable if the layout stays the same, the subfloor is sound, the vent fan can be ducted properly, and the tile area is controlled. The same bathroom can become a $35,000 project if the drain line has to move, the framing is damaged, the shower needs full waterproofing correction, the electrical is outdated, and inspections add days between rough-in and close-in.
Kitchen pricing behaves the same way. A minor kitchen refresh might include cabinet paint or refacing, new hardware, a sink, faucet, backsplash, lighting, appliance swap, and resilient flooring. A full kitchen remodel may involve a cabinet package, stone counters, new circuits, plumbing relocation, gas work, flooring transitions, drywall, trim, and inspections. Borrowing $25,000 for the first project can be reasonable. Borrowing $25,000 for the second may leave the homeowner short before countertops are installed.
Best Uses of Borrowed Money Before Selling
When the goal is resale, the smartest work is not always the most dramatic work. Buyers respond to clean, safe, well-maintained homes. Inspectors look for functional systems and visible defects. Appraisers and agents care about comparable sales, not just premium finishes.
For pre-sale improvement, we usually prefer high-visibility, lower-risk projects first: entry door replacement, garage door replacement, exterior paint touch-ups, flooring repair, minor kitchen refresh, bath refresh, lighting, hardware, safety fixes, landscaping cleanup, pressure washing, gutter repair, and obvious water-management corrections.
The 2025 Cost vs. Value national averages give helpful context. Garage door replacement showed about $4,672 in cost and $12,507 in resale value. Steel entry door replacement showed about $2,435 in cost and $5,270 in resale value. Manufactured stone veneer showed about $11,702 in cost and $24,328 in resale value. A minor midrange kitchen remodel showed about $28,458 in cost and $32,141 in resale value.
Those figures do not guarantee a return in every market. They do show a pattern we see in the field: visible exterior work and modest, well-controlled interior updates can perform better than luxury upgrades installed right before listing. A buyer may appreciate a $90,000 chef’s kitchen, but they may not pay you back dollar for dollar if the rest of the house still has an old roof, moisture stains, tired bathrooms, and an obsolete electrical panel.
For older or storm-exposed homes, water management often deserves priority over cosmetics. Start with the roof, flashing, gutters, downspouts, grading, foundation drainage, windows, siding penetrations, bath ventilation, and kitchen ventilation. A fresh paint job over moisture damage is a short-term disguise, not an improvement. Buyers notice. Inspectors notice faster.
Free tools Windows power users keep installed
One-click scans. No signup required.
Financing Cost: The Payment Still Has to Make Sense
Borrowed money has a construction cost and a finance cost. As of July 2026 reporting, average home equity loan rates were around 8.12 percent. Actual rates depend on credit score, loan-to-value ratio, debt-to-income ratio, term, lender type, property condition, and borrower documentation.
That means a $40,000 project is not just a $40,000 decision. At roughly 8 percent, interest can be significant if the loan is carried for years. For a sale-prep project, the question is often whether the improvement will help the home sell faster, sell for more, avoid repair concessions, or prevent a closing delay. For a long-term ownership project, the question is whether the improvement solves a real livability, safety, energy, durability, or value problem.
We recommend comparing three numbers before borrowing: the hard construction cost, the expected finance cost, and the realistic value of the outcome. The outcome may be resale recovery, avoided damage, reduced utility use, safer occupancy, or simply a home that works better for the family. Not every good project has a resale payback. A failing sewer line, unsafe deck, leaking roof, or overloaded electrical panel may be necessary even if it does not photograph well.
Permits, Codes, and Inspections Are Not Optional Details
Most homeowners underestimate permit time. A simple trade permit may be issued quickly in some jurisdictions. A structural change, addition, major electrical upgrade, plumbing relocation, window change in a wind zone, floodplain improvement, or work affecting life safety can require plan review and multiple inspections.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Current consumer cost guides place many building permits in the $150 to $3,000 range, while typical reported ranges run from $525 to $3,114. Complex renovations can reach about $8,500 when plan review, trade permits, reinspections, certificates of occupancy, and expediting fees are included. The bigger cost, however, can be time. A failed rough-in inspection can hold drywall. A delayed final can hold occupancy approval. A missing permit can surface during a sale and force concessions, retroactive inspections, or corrective work.
Common Projects That Often Need Permits
Permit rules vary by city and county, but homeowners should expect permits for structural framing changes, additions, deck construction, major electrical work, panel upgrades, new circuits, plumbing relocation, water heater replacement in many areas, HVAC replacement, gas lines, window or door openings, roofing in many jurisdictions, sewer work, and substantial remodeling that opens walls.
The International Residential Code framework gives local building officials authority over construction, inspections, approvals, and certificates where adopted. Local amendments matter. A contractor who works in your city should know which work can be done over the counter, which requires drawings, and which inspections are required before work is concealed.
Older Homes and Lead-Safe Work
Homes built before 1978 can trigger lead-safe work requirements when painted surfaces are disturbed. That matters during window replacement, siding work, demolition, scraping, sanding, door replacement, trim removal, and many kitchen or bath remodels. Homeowners should ask whether the contractor is properly certified for lead-safe renovation when required and how dust containment, cleanup, and occupant protection will be handled.
Floodplain Substantial Improvement Rules
If a home is in a mapped floodplain, large repairs or improvements can trigger substantial-improvement rules. A common threshold is 50 percent of the structure’s market value, though local enforcement and documentation requirements matter. Crossing that line can require elevation, flood-resistant materials, or other compliance work. Before financing a major remodel on a floodplain property, confirm the rules with the local floodplain administrator.
How Draw Payments Should Work
Payment structure is one of the clearest places where financing platforms, homeowners, and contractors need discipline. The safest approach is to tie payments to observable milestones, not calendar dates or vague progress claims.
Rank #3

- PERFECT FOR RECORD KEEPING: The 1 Pack account ledger books are versatile and can be used to track finances, budgets, expenses, and other business or personal records. They are perfect for individuals, entrepreneurs, or small business owners who need a reliable and efficient way to keep track of their finances. With 50 pages, customers can record transactions over an extended period, making it a handy tool for financial planning and organization.
- COMPACT AND LIGHTWEIGHT: The account ledger books are compact and lightweight with each book weighing 7 ounces and measuring 8.5 x 6.25 inch, making them easy to carry around. You can take them with them in a bag or briefcase, making them ideal for on-the-go use. This feature ensures that you can access your records at any time, whether you are at work or on the move.
- DURABLE KRAFT COVER: The kraft cover is a distinguishing feature of these account ledger books. It provides a durable layer of protection that can withstand daily wear and tear, making it suitable for long-term use. Additionally, the classic, rustic appearance of the cover gives it a timeless and professional look that can fit in any setting.
- PREMIUM QUALITY: Elegant style with the words ''Account Tracker'' embossed in fancy Gold Foils. The gold coil ring binding is a practical design feature that enhances the functionality of the account ledger books. It allows pages to turn smoothly and easily, making it effortless to flip through the book while keeping pages in place. The ring binding also ensures that pages won't fall out, preventing the loss of vital information.
A reasonable draw schedule depends on project size, materials, and contractor capacity, but the principle is consistent. Money should move when work reaches a defined stage. For example, a remodel might include mobilization, demolition completion, rough-in inspection, close-in approval, cabinet or finish installation, substantial completion, and final inspection or punch-list completion.
For a larger project, the homeowner may see a deposit, then draws at 20 percent, 40 percent, 60 percent, 80 percent, and final completion. For a smaller repair, there may be a modest deposit, one progress payment, and a final payment. Custom materials can require separate deposits because cabinets, windows, doors, and special-order fixtures may not be returnable.
The red flag is not any deposit. The red flag is a large upfront payment with no material order, no permit, no schedule, no milestone, and no lien protection. Final payment should not be released until the punch list is complete, required inspections are signed off, manuals and warranty documents are delivered, and lien waivers are collected from the contractor and applicable subcontractors or suppliers.
Contractor Vetting Still Belongs to the Homeowner
A platform-approved contractor or service provider may be a helpful starting point, but homeowners should still verify local requirements. Construction is local. Licensing, insurance, bonding, permit rules, lien rights, and warranty obligations vary by state and municipality.
Before signing, ask for the contractor’s license number where licensing applies, general liability insurance certificate, workers’ compensation coverage, written scope, payment schedule, permit responsibility, change-order procedure, warranty terms, and expected start and completion windows. Ask who will be on site, who supervises subcontractors, and how inspections are scheduled.
The contract should say what is included and what is excluded. “Bathroom remodel” is too loose. Better language identifies demolition, plumbing fixtures, shower waterproofing system, tile areas, grout type, exhaust fan ducting, electrical fixtures, drywall repair, paint, trim, disposal, permits, inspections, and allowances. If the vanity allowance is $1,200, say $1,200. If tile is priced at $6 per square foot material cost, say that. Allowances protect both sides when selections are not final.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteChange orders should be written, priced, and approved before the work is performed unless there is an emergency condition. A homeowner should know whether change orders include labor, materials, subcontractor markup, overhead, profit, permit adjustments, schedule impact, and tax. Vague change orders are where many financed projects lose control.
When to DIY vs. When to Hire a Pro
DIY can make sense when the work is low-risk, visible, reversible, and outside permit-sensitive systems. Painting, simple landscaping cleanup, cabinet hardware replacement, basic shelving, minor caulking, door knobs, some fixture swaps, and deep cleaning can be good homeowner projects. A careful homeowner can improve presentation before listing without taking on structural, electrical, plumbing, or waterproofing risk.
DIY becomes a poor bet when failure can damage the house, injure someone, void insurance, delay a sale, or require concealed inspection. Hire a pro for structural framing, load-bearing wall changes, roofing, deck framing, stairs, electrical panels, new circuits, gas lines, plumbing relocation, shower waterproofing, sewer work, HVAC replacement, window opening changes, foundation repairs, and anything requiring engineered drawings.
Bathrooms are a good example. Painting a vanity and replacing hardware may be reasonable DIY work. Building a site-built shower is not a casual weekend project. Proper slope, drain assembly, waterproofing membrane, inside corners, curb details, flood testing, backer board, vapor considerations, and ventilation all matter. A shower can look finished for six months and still be leaking into the framing.
For sale-prep work, DIY should also be judged by schedule. If a homeowner has three weeks before listing, a half-finished DIY floor can cost more than hiring a crew from the start. Buyers do not give credit for intention. They see the condition on the day of showing.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Energy Upgrades, Rebates, and Tax Credits
Energy improvements can be good candidates for financing when they solve comfort, operating cost, or equipment reliability problems. Common examples include heat pumps, insulation, air sealing, efficient windows, exterior doors, electrical panel upgrades related to electrification, and qualified HVAC or water-heating equipment.
The federal Energy Efficient Home Improvement Credit can help with eligible improvements, but homeowners should verify current IRS rules, product qualifications, annual limits, and documentation before assuming a credit. DOE home upgrade rebates are state-administered, and availability varies by location. Some programs open later than others, run out of funding, or require approved contractors and pre-work documentation.
From a construction standpoint, do not let a rebate drive a bad sequence. Air sealing and insulation may need ventilation review. New windows may need flashing and water-resistive barrier details. A heat pump may need electrical capacity checks. A panel upgrade may trigger utility coordination, permit review, and inspection. The incentive is only useful if the finished work is durable, legal, and appropriate for the house.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Repair Windows errors before they cause bigger problems3Fix the driver behind crashes, sound loss and screen glitchesCommon Mistakes With Financed Remodels
The first mistake is borrowing from a rough idea instead of a written scope. That leads to underfunding, delayed decisions, and expensive change orders. A homeowner who borrows $30,000 for a kitchen based on photos may discover the real project is $48,000 once cabinets, electrical, flooring, drywall, permits, and contingencies are priced.
Rank #4

- Used Book in Good Condition
The second mistake is choosing cosmetics while ignoring defects. A buyer will notice new counters, but their inspector will still flag roof leaks, drainage problems, electrical hazards, HVAC failure, structural movement, moisture stains, unsafe stairs, or missing GFCI protection where required. Durable repairs should come before decorative upgrades when the budget is tight.
The third mistake is assuming a financing platform automatically handles licensing, insurance, permits, and workmanship. It may help coordinate payment and access to capital. It may have provider standards. The homeowner still needs to verify local compliance and contract terms.
The fourth mistake is starting before permits are issued. Stop-work orders, reinspection fees, delayed closings, uncovered walls, or required demolition of concealed work can wipe out any schedule advantage. If a project needs a permit, build that time into the listing plan.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →The fifth mistake is paying too much upfront or releasing final payment too early. Final payment is leverage for completion, documentation, cleanup, warranty delivery, lien waivers, and inspection signoff. Once all the money is out, the homeowner’s options narrow.
A Practical Homeowner Checklist Before Borrowing
Before using any home improvement financing platform, get the construction side in order. Start with a written scope from a qualified contractor. Confirm whether the scope is fixed price, cost-plus, or allowance-based. Ask what is excluded. Verify license and insurance. Confirm permit responsibility. Ask whether drawings, engineering, or HOA approval are required.
Next, review the payment plan. Tie draws to milestones such as mobilization, rough-in inspection, close-in approval, substantial completion, and final inspection. Require written change orders. Keep a contingency, usually 10 percent for straightforward cosmetic work and 15 to 25 percent for older, concealed, or system-heavy projects.
Then compare the financing terms to the project outcome. Look at interest rate, fees, repayment term, lien position, prepayment rules, and what happens if the home does not sell as quickly as expected. If the financing is tied to a sale, ask what happens if the closing is delayed 30, 60, or 90 days.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallCrashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteFinally, protect the closeout. Collect inspection approvals, lien waivers, warranty information, product manuals, paint colors, fixture model numbers, and before-and-after photos of concealed work when available. Those documents can matter during a sale and later if a warranty issue appears.
The Bottom Line for Homeowners
HouseAmp’s $12.4 million raise shows that home improvement financing is becoming more organized and more connected to real estate transactions. That is useful. Many homeowners need a bridge between the work their house needs and the cash they have on hand.
But the best use of borrowed money is disciplined construction. Finance the right scope. Price the real work. Pull the required permits. Use milestone draws. Verify the contractor. Keep contingency. Choose improvements that match the house, the market, and the reason for the project.
A good contractor will sometimes reduce the scope, not expand it. If the home needs drainage correction, safe wiring, a sound roof, working ventilation, and clean inspection items, that may be a better use of financing than premium tile or luxury appliances. Equity is protected by durable work, not just new finishes.
Frequently Asked Questions
What is HouseAmp and how does it help homeowners finance improvements?
HouseAmp is a fintech platform founded in 2020 that provides lending and payment infrastructure for homeowners, real estate agents, lenders, and service providers. It can help fund repair or remodel work, especially around sale preparation, but homeowners still need written scopes, permits, inspections, and contractor verification.
Is home improvement financing a good idea before selling a house?
It can be, if the work removes buyer objections, solves inspection issues, or improves marketability more than the financing cost. It is risky when homeowners borrow before receiving a real scope, ignore permit requirements, or spend on premium finishes while leaving roof, drainage, electrical, HVAC, or structural problems unresolved.
How much does a typical remodel cost in 2026?
HomeAdvisor reports a 2026 whole-home renovation average around $52,133, with a broad $3,000 to $190,000 range. Angi reports kitchen remodels averaging around $26,942, typically $14,589 to $41,547. Bathroom remodels commonly range from about $8,000 to $45,000 depending on plumbing, waterproofing, tile, fixtures, and ventilation.
Which home improvements usually need permits?
Permit rules vary locally, but permits are commonly needed for additions, structural framing changes, decks, electrical panel work, new circuits, plumbing relocation, HVAC replacement, gas lines, major roofing, sewer work, and remodels that open walls or affect life safety systems.
Free tools Windows power users keep installed
One-click scans. No signup required.
How should renovation payments or draws be structured?
Payments should be tied to visible milestones, not just dates. Common milestones include mobilization, demolition completion, rough-in inspection, close-in approval, finish installation, substantial completion, punch-list completion, and final inspection. Final payment should wait until required approvals, lien waivers, warranty documents, and cleanup are complete.
What can go wrong if remodeling work is done without permits?
Unpermitted work can lead to stop-work orders, reinspection fees, delayed closings, insurance problems, required demolition of concealed work, buyer objections, appraisal issues, and expensive corrections. Permit time should be built into the project schedule before listing or financing decisions are finalized.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.